UPI expands from code scanning to proximity payment
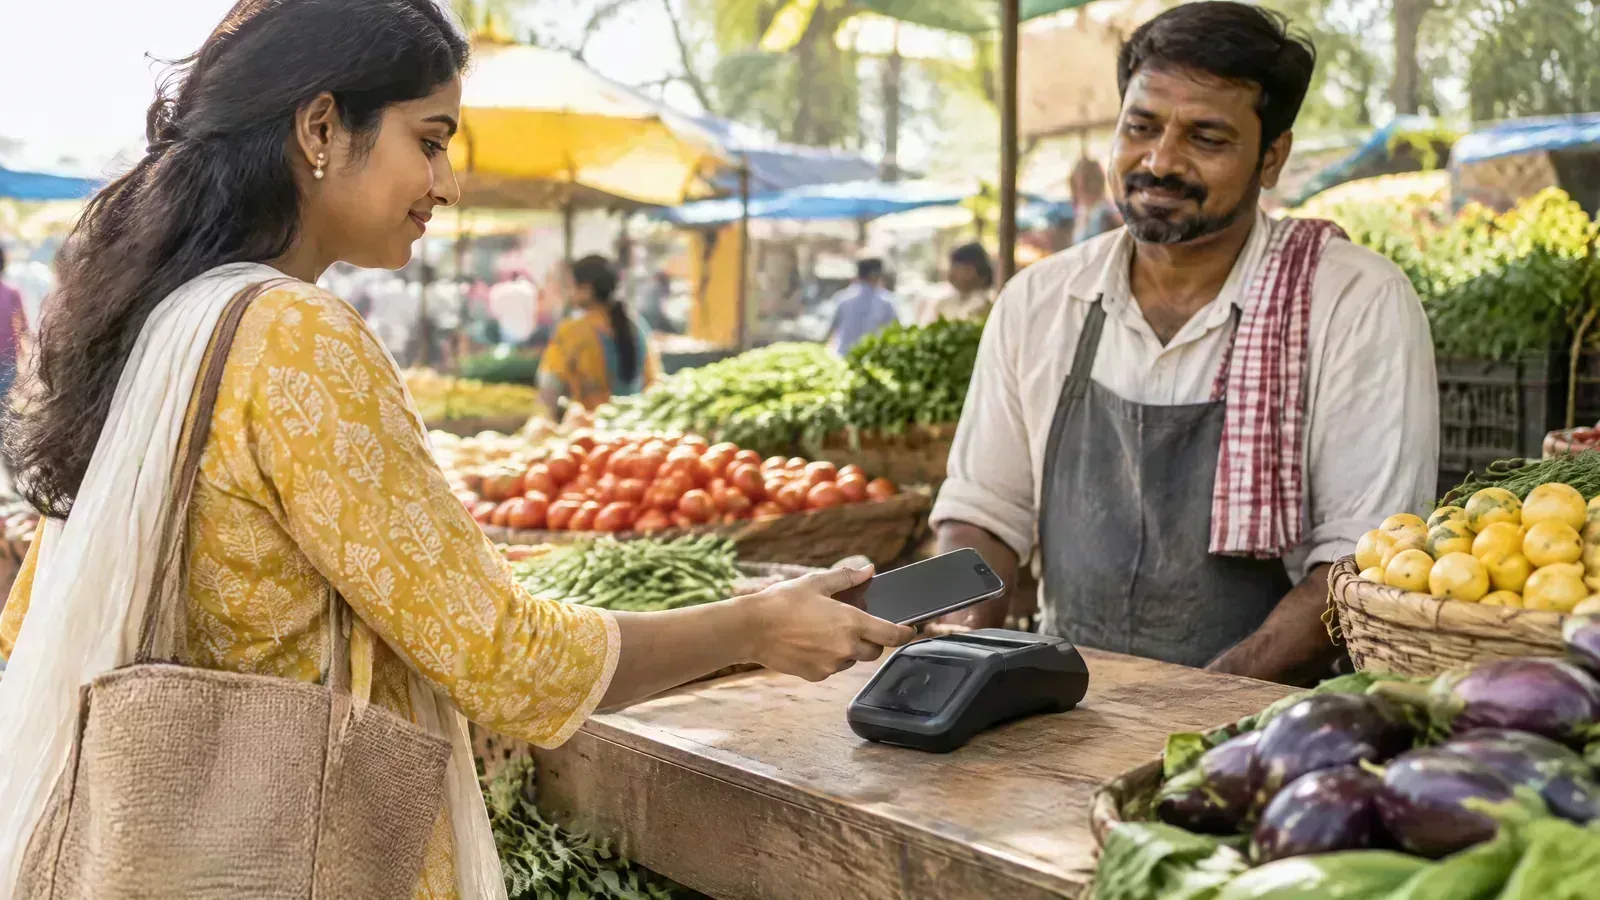
NPCI introduced a UPI tap-to-pay option that lets a compatible phone communicate with a point-of-sale terminal through near-field communication. Reuters reported that the design is intended to work in low- or no-connectivity conditions. [1]
Moneycontrol reported PIN-less transactions up to ₹5,000. The limit, supported devices, terminal coverage, issuer participation and availability conditions should be checked in each live implementation rather than assumed to be universal. [2]
MyUPI adds a domain-specific support interface
The same launch package included MyUPI, an AI-assisted customer-support capability built around NPCI’s domain-specific language-model work. Its practical value will depend on the accuracy of answers, escalation to people and access to authoritative transaction evidence. [1] [2]
Customer support in a payment system must connect intent classification to dispute, reversal, fraud and complaint workflows. A conversational layer does not itself resolve who owns an exception or how quickly money is restored. [1] [2]
Controls must develop with the new interface
Useful operating evidence will include authentication rules, offline limits, lost-device controls, terminal certification, false-decline rates, reversals and customer outcomes across languages and accessibility needs. [1] [2]
finorasjournal reports the feature launch for information. It does not claim guaranteed security, universal acceptance or suitability for any particular user or merchant. [1] [2]