AI
Explainable AI in finance is moving from policy language to control design
Financial compliance teams are asking for traceable evidence chains, change controls, and clear human escalation paths.
AI changes financial decisions only when institutions can explain the use case, data, model, owner, human escalation path and evidence. This hub connects product experimentation to governance, customer outcomes and supervisory expectations.
The same model-risk language cannot be applied blindly to customer service, fraud detection, credit decisions, compliance monitoring and supervisory technology. Each use case needs a clear decision boundary.
Documentation should connect approved purpose, data lineage, model or prompt version, validation, deployment, monitoring, change control and override outcomes. A policy without reconstructable evidence is not an operating control.
Human review works only when reviewers receive understandable evidence, enough time and real authority. Coverage therefore examines escalation design, reason codes, fairness, customer recourse and third-party dependencies.
Financial compliance teams are asking for traceable evidence chains, change controls, and clear human escalation paths.
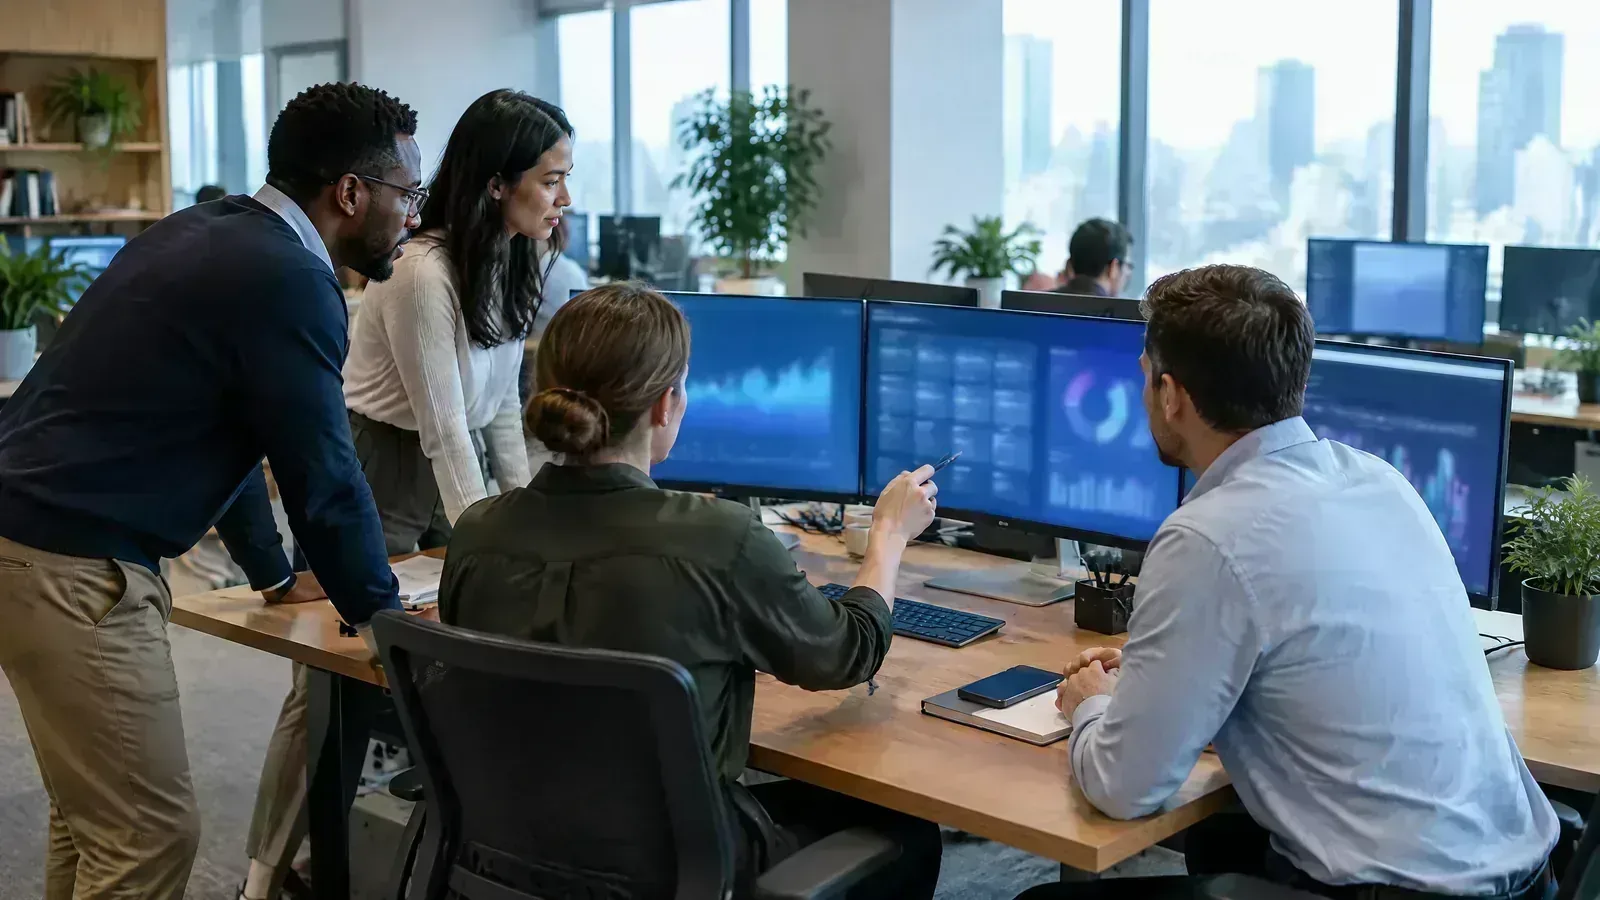
Desk grounds finance requests in ERP, HRIS and CRM records, drafts evidence-backed replies for review and preserves routing, permissions and audit history.
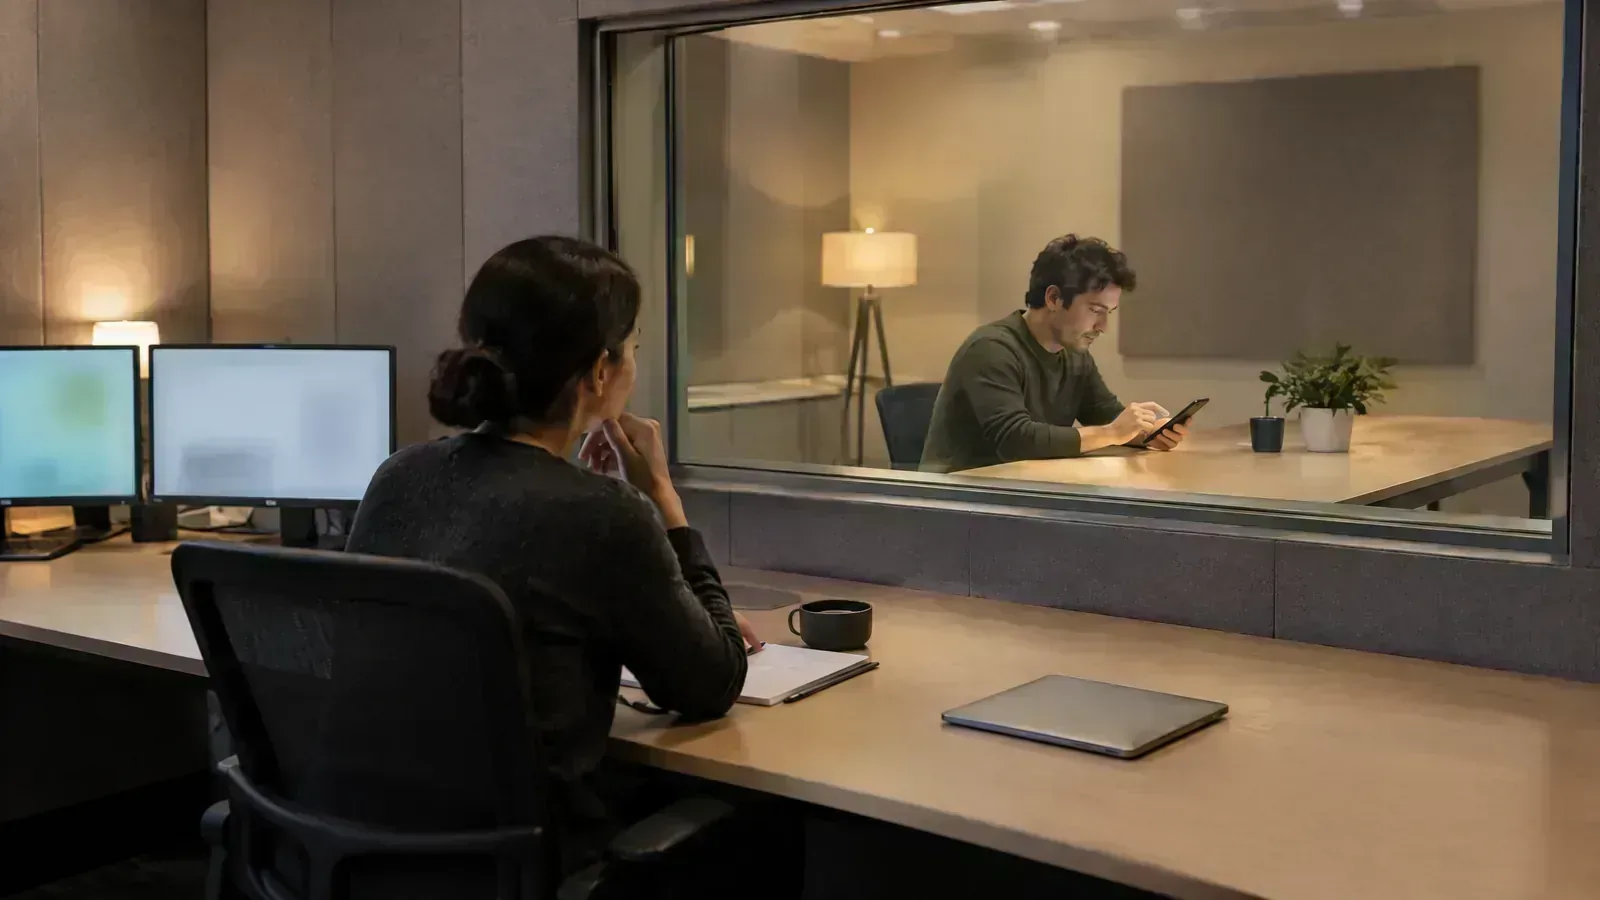
The Islamabad facility combines AI, customer research, eye tracking and rapid prototyping before financial features reach the live platform.
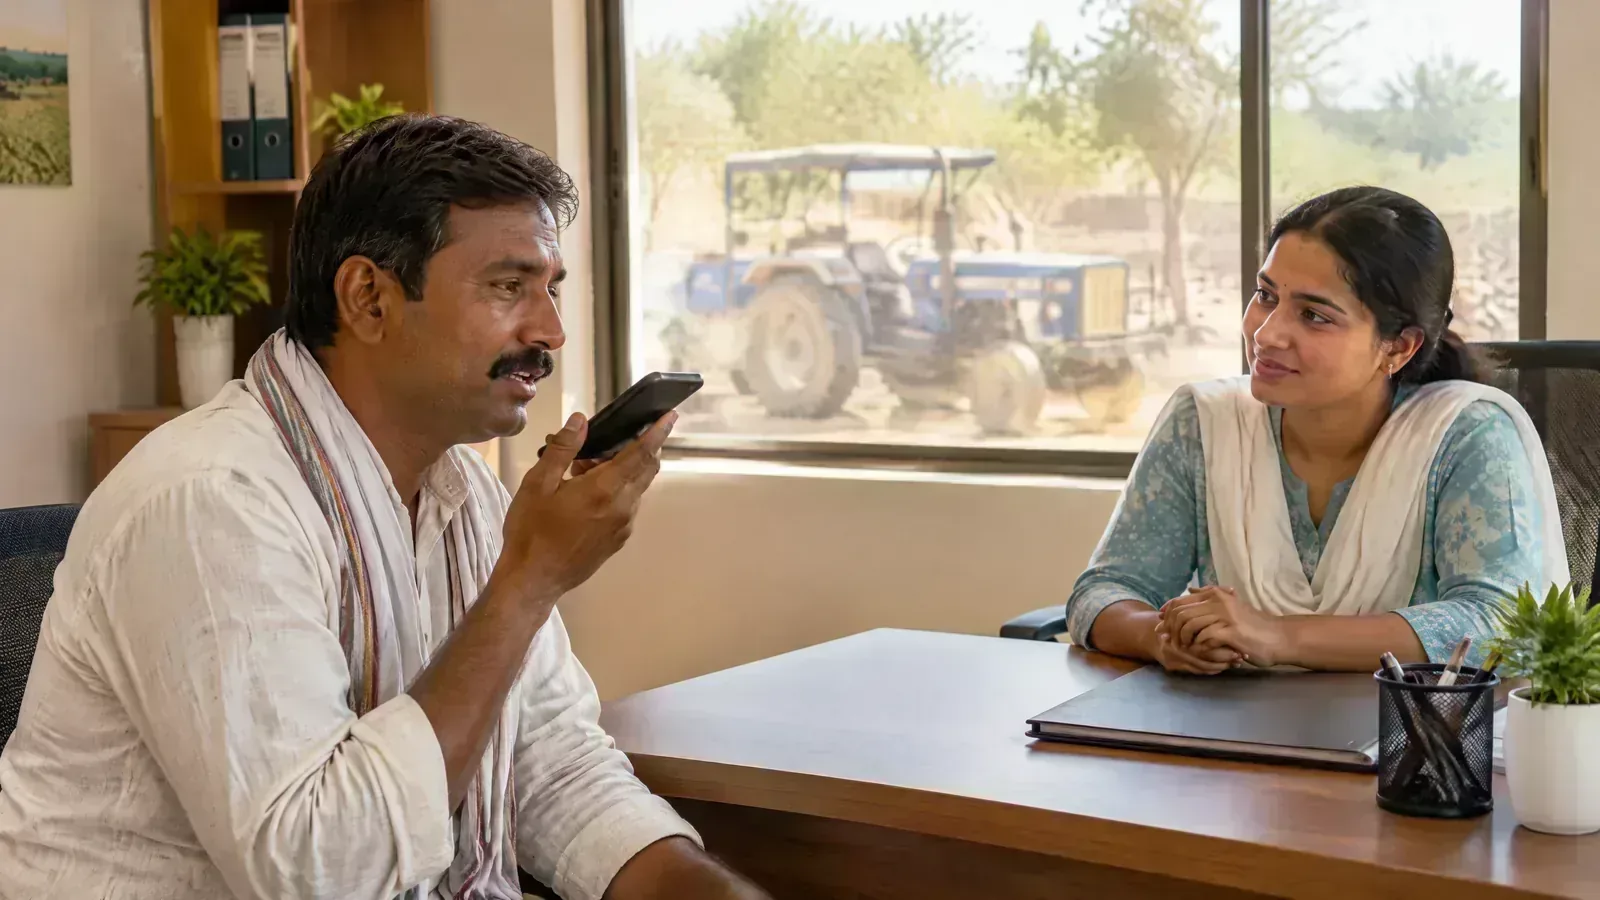
Voice agents now span sales, loan servicing, collections and field feedback across 12 Indian languages, with every scale metric explicitly company-reported.
India’s markets regulator is combining analytics, AI governance records and an IOSCO supervisory toolkit to identify emerging risks earlier.
Two central-bank ecosystem memoranda will explore first-category payment-organisation access for VEON companies and demonstrate an AI-enabled SupTech platform with Alatau City Authority.
The enhanced A2A Protect product evaluates suspect transfers before release and combines bank-local behaviour with opt-in network risk signals.